Insuring a shotgun house in New Orleans depends on the roof, wind, flood and system evidence behind each quote, because shotgun is an architectural label and not an insurance rate class. A usable quote depends on the carrier's current underwriting and the documented property: construction, roof, systems, occupancy, losses, mitigation and flood information.
Written by Ryan Roberts
Ryan Roberts is a New Orleans real estate agent focused on shotgun homes and historic residential property.
What information should accompany a shotgun house insurance quote?
The information that should accompany a shotgun house insurance quote is one verified property file, given identically to each agent or carrier. A listing's shotgun label should not substitute for the current dwelling-unit count, construction details or roof record. A converted double, operating two-family dwelling and single shotgun can present different use and system information even when their façades look related.
Start with the legal-use verification guide and the permit-history workflow when the configuration or renovation record is unclear. Use the inspection guide to identify physical questions that need specialist evidence.
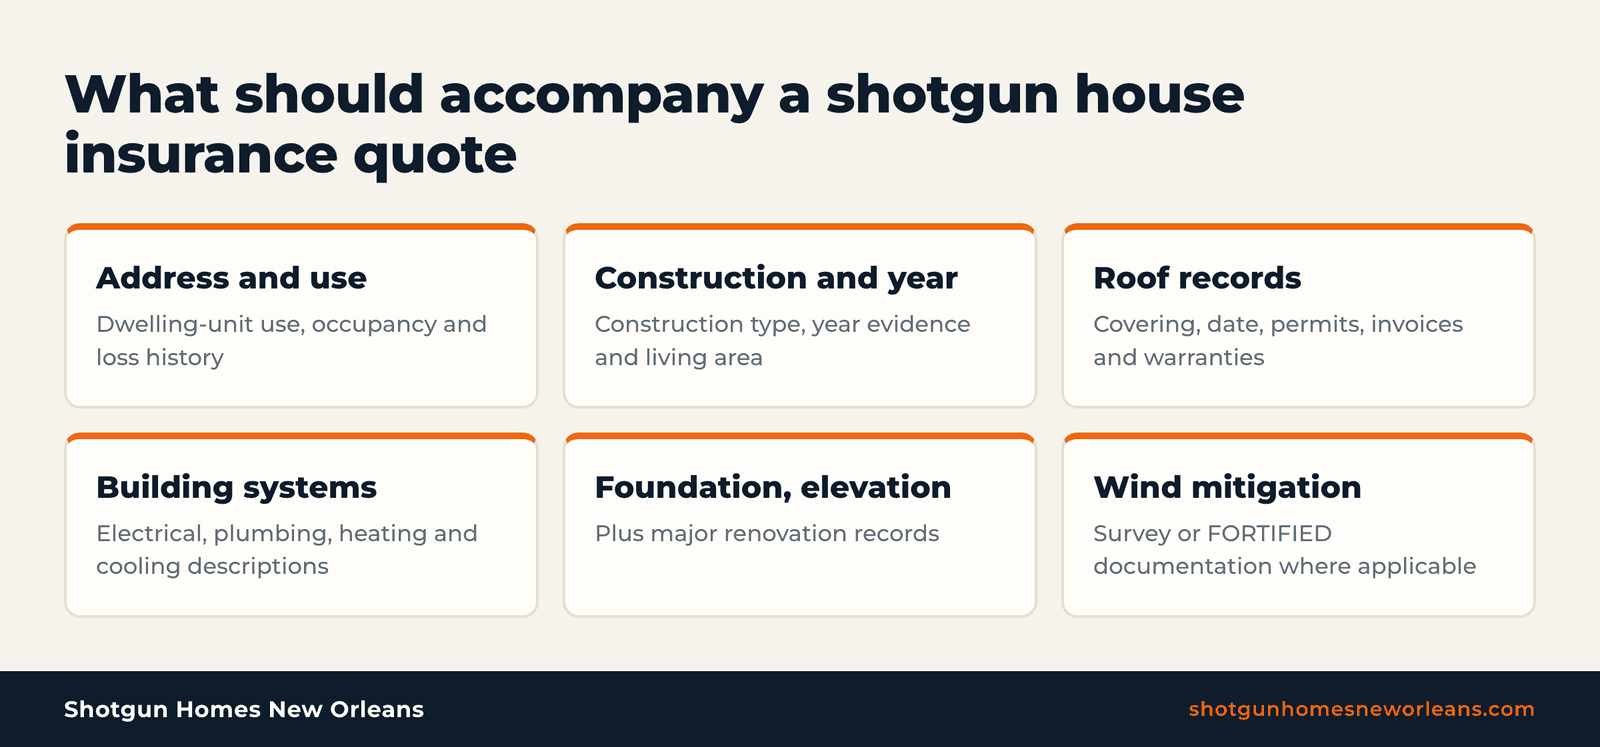
- —Exact legal and mailing address plus current dwelling-unit use
- —Construction type, year evidence and living-area source
- —Roof covering, installation date, permits, invoices and warranties
- —Electrical, plumbing, heating and cooling descriptions
- —Foundation/elevation information and major renovation records
- —Requested loss history, occupancy and rental-use information
- —Wind-mitigation or FORTIFIED documentation where applicable
How do homeowners, wind and flood questions differ for a New Orleans shotgun house?
Homeowners, wind and flood questions differ for a New Orleans shotgun house because one quote does not answer every hazard. Louisiana homeowners policies can contain specific wind or named-storm deductibles and coverage terms. Flood insurance is a separate policy decision, and NFIP building and contents coverage are distinct choices with separate deductibles.
The site's flood-zone and elevation-certificate guide owns the address-level map and certificate workflow. Its evidence informs the flood application but does not calculate a transferable premium.
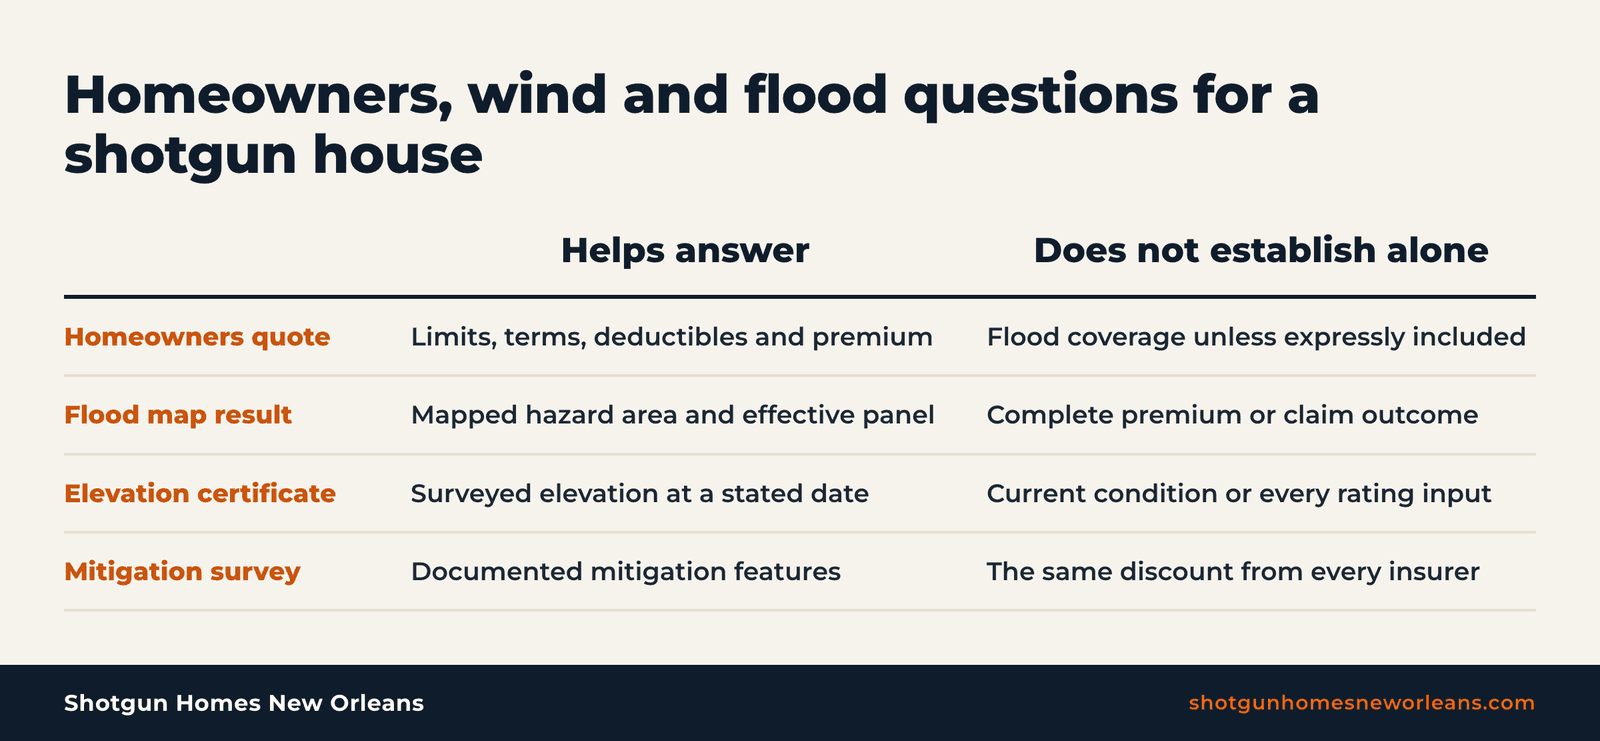
| Document | Question it helps answer | What it does not establish alone |
|---|---|---|
| Homeowners quote | Offered limits, terms, deductibles and premium | Flood coverage unless expressly included by the relevant policy |
| Flood map result | Mapped hazard area and effective panel | The complete property premium or claim outcome |
| Elevation certificate | Surveyed elevation information at a stated date | Current physical condition or every rating input |
| Wind-mitigation survey | Documented mitigation features | That every insurer offers the same discount |
Why do roof and building-system records matter for shotgun house insurance?
Roof and building-system records matter for shotgun house insurance because carriers can ask for roof age, covering and condition, along with electrical, plumbing and heating information. Supply permits, invoices and photographs that identify the completed work rather than estimating a date from appearance. If records and visible conditions conflict, resolve the discrepancy before relying on a quote.
A roof replacement, rewiring or replumbing statement should define the actual scope. One replaced panel does not mean every branch circuit changed; one roof covering does not establish the deck, fasteners or roof-to-wall connections. The quote application and insurer's questions control what documentation is required.
What can a Louisiana wind-mitigation survey establish?
A Louisiana wind-mitigation survey can establish documented features that support available premium discounts. The Louisiana Department of Insurance explains that eligible homeowners may submit a completed survey for that purpose. The survey addresses items such as roof deck attachment, roof-to-wall strength, secondary water barriers and opening protection.
Contact the insurer first to learn which documentation and discounts it recognizes, then use an authorized surveyor where the process requires one. A mitigation feature should not be assumed from a renovation description, and a survey does not guarantee a specific discount or policy offer.
How should multiple insurance quotes be compared?
Multiple insurance quotes should be compared on normalized coverage before price. Put limits, replacement-cost or actual-cash-value treatment, deductibles, named-storm terms, exclusions, endorsements, loss-of-use terms, liability, rental-use treatment and effective dates side by side. Ask the agent to explain material differences in the policy documents.
For a purchase, request quotes while inspection and financing contingencies can still respond to the result. For planned work, tell the carrier about vacancy, construction, additions or unit changes before assuming ordinary occupancy coverage continues unchanged.
Frequently asked questions about insuring a shotgun house
Is a shotgun house automatically more expensive to insure?
No, a shotgun house is not automatically more expensive to insure; the carrier evaluates the documented property, coverage request, underwriting rules and current market at the time of application.
Is flood insurance included in homeowners insurance?
No, flood insurance is not included in standard homeowners insurance unless the policy expressly says so; the two are separate coverage questions. Obtain and compare the actual policy documents and a property-specific flood quote.
Why does roof documentation matter for a quote?
Roof documentation matters for a quote because it can establish the covering, installation date and scope more reliably than appearance or a listing statement. Insurers decide which roof evidence they require and how it affects underwriting.
Can a wind-mitigation survey reduce a premium?
Yes, a wind-mitigation survey can reduce a premium when the insurer recognizes the documented mitigation for an available discount under Louisiana's process. I contact the insurer first, because survey eligibility and the resulting discount are not guaranteed.
When should a buyer request insurance quotes?
A buyer should request insurance quotes early enough to resolve missing roof, use, flood or system information and evaluate the offered terms before contractual and financing deadlines.
Key takeaways
- 01Quote the documented property and current use, not the shotgun label.
- 02Separate homeowners, wind and flood coverage questions.
- 03Use permits, invoices and surveys to support roof and mitigation statements.
- 04Compare identical limits, valuation, deductibles, exclusions and endorsements.
- 05Only the insurer, licensed agent and policy documents determine coverage and price.
References
- 01Consumer publications
Louisiana Department of Insurance
- 02Wind mitigation incentives
Louisiana Department of Insurance
- 03Protecting your home
Louisiana Department of Insurance
- 04Buy a flood insurance policy
National Flood Insurance Program
My methodology
Open each item to see the scope, definitions and limits behind the article.
Research date+
Current Louisiana Department of Insurance and National Flood Insurance Program resources were reviewed on September 4, 2026.
Insurance boundary+
This guide does not quote, interpret or recommend a policy. Current insurers, licensed agents, applications and policy documents control property-specific availability and coverage.
Overlap boundary+
Flood mapping and elevation certificates remain on the site's dedicated flood page; this article focuses on quote preparation and policy comparison.